
















Fintech Software Development Company

Your banking-as-a-service platform got you to market. Now its configuration layer is the ceiling: the risk model you cannot express, the ledger you cannot prove, the compliance workflow it only half covers. We build the financial software your platform cannot.

  • Payment platforms with idempotent processing: money moves exactly once

  • Digital banking cores on double-entry ledgers you can prove balance

  • Lending systems with underwriting engines built to your credit policy

  • KYC/AML tooling that treats identity as a lifecycle, not a checkbox

3+ years RetentionWeek 1 First milestoneFixed price Pricing

The problem

Sound familiar?

  • Building on a white-label platform that covers 80% of your product but forces workarounds for the 20% that differentiates you?

  • One sponsor bank standing between your product and an overnight shutdown?

Short answer

RaftLabs builds custom fintech software: payment platforms, digital banking cores, lending origination and servicing, and KYC/AML compliance tooling for fintech startups, challenger banks, and financial institutions across the US, UK, and Australia. Ledgers are double-entry and provable, compliance is designed in from the first sprint, and integrations are scoped against what your providers actually expose. Most projects deliver in 10 to 16 weeks ($50K to $120K) at a fixed cost agreed before development starts.

Who this is for

Fintech teams we build for

Fintech startups

Payment platforms and lending products that launch as a validated v1 in 10 to 16 weeks.

Challenger banks

Digital banking cores on a double-entry ledger your auditors can verify.

Lenders

Origination and servicing with an underwriting engine built to your credit policy, not a generic template.

Financial institutions

KYC/AML compliance tooling and transaction monitoring that holds up under regulatory review.

01 Diagnosis

Problems we solve in fintech

  1. 01
    Problem

    Your ledger doesn't balance

    Solution

    Most fintechs hold customer money in one or two pooled accounts and track individual balances in a ledger built on top. When that ledger is buggy, the shortfall is not embarrassing, it is existential: customer balances on screen exceed the money actually held, and no fraud is required, just ordinary engineering sloppiness. We design the ledger first, double-entry by construction, with automated reconciliation matching provider events to ledger entries in real time. The result is balances you can prove, to your customers, your auditors, and your sponsor bank.

  2. 02
    Problem

    Your sponsor bank is a single point of failure

    Solution

    One BaaS provider, one sponsor bank, one consent order or changed risk appetite, and your product can be disrupted overnight, with customer funds frozen while providers dispute the balances. We have all watched it happen. So we architect the money-movement layer separated from any single provider, keep balances provably yours, and plan the migration path before you need it. The result is a product no single partner can take down.

  3. 03
    Problem

    KYC was a checkbox at onboarding. Now it's a liability.

    Solution

    Documents expire, risk classifications move, screening results change, yet most systems treat VERIFIED as a permanent attribute set once at onboarding. Then an audit asks what you knew and when, and the answer is a spreadsheet. We build identity as a lifecycle: event-driven reverification, real-time transaction monitoring against your risk rules, and a triage queue your compliance team can actually clear. The result is compliance that survives audits years after launch.

  4. 04
    Problem

    Licensing will take longer than the build

    Solution

    US money transmission can mean 40+ state licenses over 6 to 18 months. Your app can be ready and still unable to legally launch. Most teams discover this after the architecture is set, when the only options left are expensive. We put the license strategy in discovery, before a line of architecture exists: operate under a regulated partner's license for speed, pursue your own where the economics demand it, and sequence the two honestly. The result is a launch date you can defend.

02 What we ship

Fintech software we ship

  1. Payment platforms

    Payment processing across Stripe, Adyen, and direct acquiring networks, so you are not locked to a single gateway. Multi-currency settlement and FX sit alongside reconciliation automation that matches payment events to ledger entries and flags discrepancies before end-of-day. Processing is idempotent: a retried payment credits exactly once, even when the provider's response never arrives. Money moves exactly once.

  2. Digital banking cores

    Core account management on a double-entry ledger, with transaction history and balance calculation your auditors can verify. Current and savings configuration, card issuance and controls, and open banking connectivity under PSD2 cover the product surface customers expect. Digital KYC onboards without a manual review queue. A core you can prove balances.

  3. Lending platforms

    Origination with application intake, bureau integration, and an underwriting engine built to your credit policy, not a generic risk template. Servicing covers repayment schedules, arrears, early settlement, and collections. Open banking affordability assessment replaces manual bank-statement review. Decisions in seconds, applied consistently.

  4. KYC/AML and RegTech

    Digital identity verification with document checks, liveness, and real-time PEP/sanctions screening, built as a lifecycle rather than a gate. Transaction monitoring with configured rules and alert triage replaces the spreadsheet your team reviews a month late. SAR workflows and a complete audit trail mean the next regulatory review finds everything it needs. Onboarding in minutes, compliance that holds up.

  5. Wealth and investment platforms

    Portfolio management with multi-asset support, performance calculation, and rebalancing. Robo-advisory with risk profiling and model portfolios. Custody integrations and suitability assessments for regulated markets. A platform that scales past the spreadsheets.

  6. Finance automation

    The operational layer around the money: reconciliation, fee computation, payout scheduling, and regulatory reporting, automated. AI agents for underwriting assistance, fraud review, and reporting where the volume justifies them. An operations team that grows slower than your transaction volume.

Integrations

Works with the systems you already run

Integrations are scoped against what your providers actually expose, before architecture, not during the build.

Payments
Stripe · Adyen · Direct acquiring networks
Banking and identity rails
Open banking (PSD2) · Credit bureau integrations · KYC/AML providers
You are not locked to a single gateway.

03 Buy, build, or wait

Your license decision comes before your build decision.

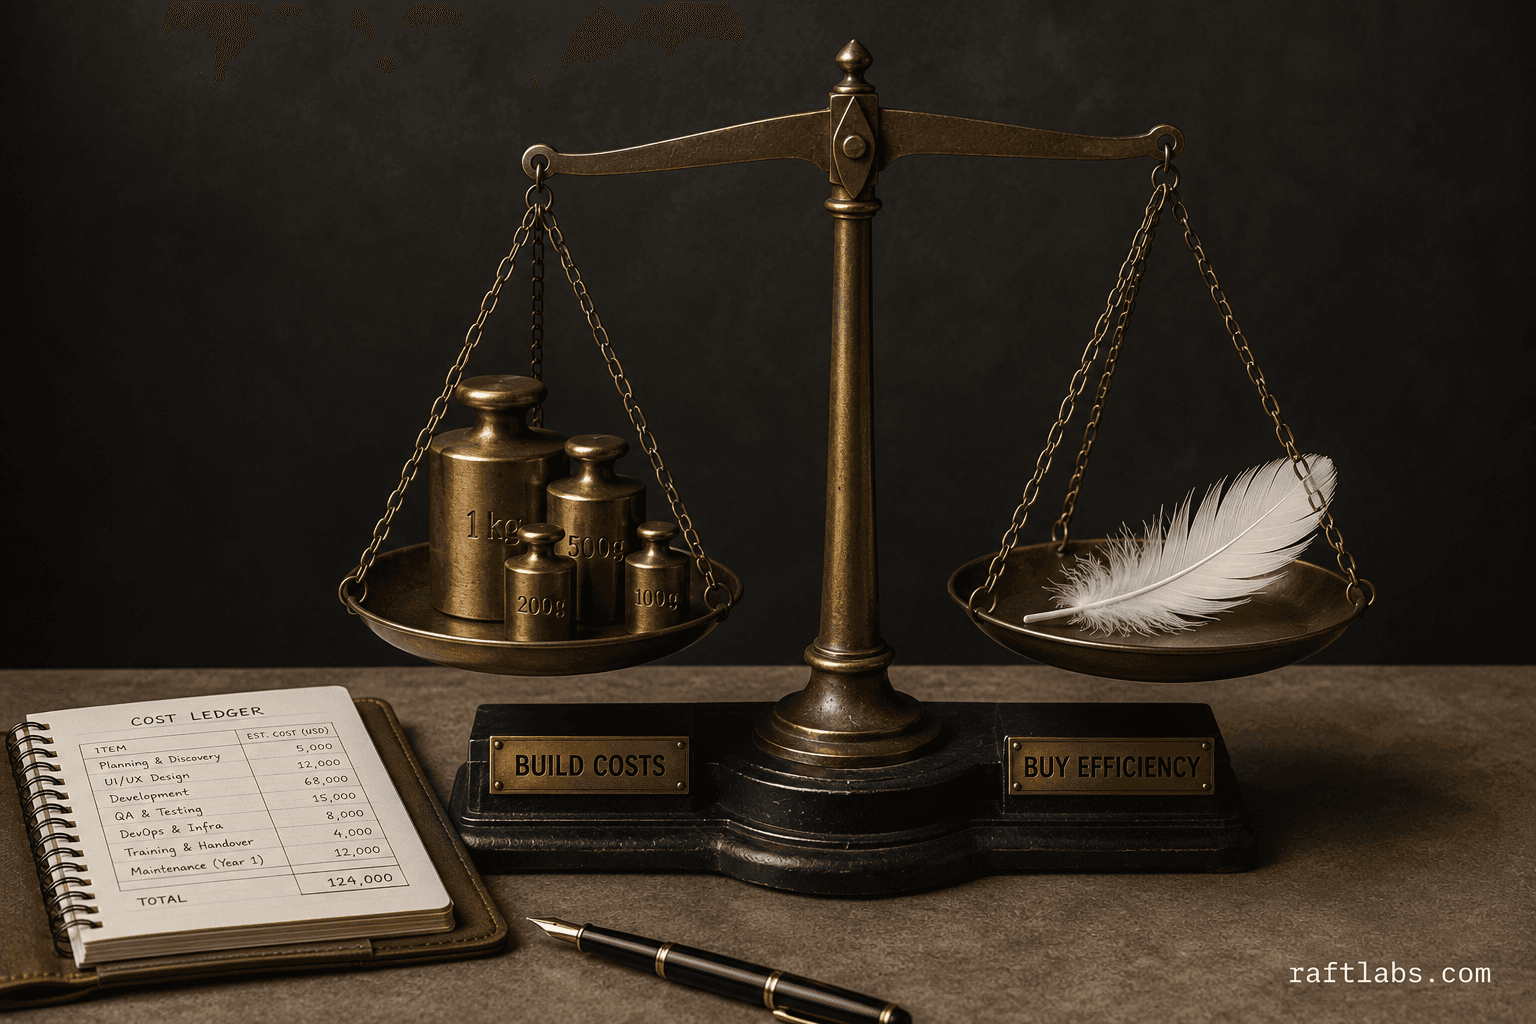
The live question is not build versus buy software. It is whether to operate under a partner's license or pursue your own, and what to build once that decision is made.

Stay on the platform

  • Standard products

    Wallets, savings, and simple lending launch in weeks on BaaS, with the compliance heavy lifting handled.

  • Brand differentiation

    When the difference is brand and distribution, not behavior, the platform's 80% is enough.

  • Partner license, year one

    Operating under a regulated partner is the pragmatic answer while volume is unproven.

Build custom

  • Differentiation the config layer can't express

    Custom risk models and account structures that don't fit the platform's data model.

  • Volume economics

    Platform pricing becomes a constraint at scale; owning the stack changes the unit economics.

  • The money layer itself

    The ledger and compliance core you must be able to prove. This is never rented blindly.

Bottom line

You can always add features. You can't un-spend six months of runway. Decide the license strategy before the architecture.

04 How we work

How we build fintech software

  1. 01

    Discovery and license strategy

    We map the financial product, the regulatory permissions, the payment flows, and the provider landscape. The license question gets answered here, not after the build: partner license, direct licenses, or both sequenced. The risk this retires: building a product you cannot legally launch.
  2. 02

    Architecture and ledger design

    The data model is designed around the money: double-entry ledger structure, idempotent transaction processing, the underwriting logic, and the compliance workflow. FCA, PSD2, and GDPR obligations are factored in before any code is written. The risk this retires: the ledger bug, the single defect class that can end a fintech.
  3. 03

    Build in sprints

    Two-week sprints with working software at each checkpoint. The transaction core or lending workflow ships first; compliance infrastructure, reporting, and partner integrations follow. The risk this retires: the fintech wall, where a generalist team discovers mid-project that money has rules.
  4. 04

    Launch and compliance hardening

    Phased go-live starting with a controlled cohort, then penetration testing and the audit-ready documentation package: data flows, access matrices, and the evidence your compliance team needs. The risk this retires: the retrofit, paying for compliance twice because it was designed in late.
Perceptional logo
Musgrave Group
UrShipper logo
Brux Dental Solutions
Bella Skin Institute Logo
Energia Rewards
Draftly logo
TuneClub Logo
Sekou LMS logo
Logo of food order management app gula
SnelwegDeals
Grubly logo
PSi logo
Instantor Rewards logo
logo of Mobile app for events, membership clubs, and communities
AldiFest retail campaign logo
Vidmattic logo
EMS Connect logo
Worx Squad logo
logo of Online Web App For Making Intro
logo of Referral and Viral Marketing Platform
Concurrences logo
GE logo
Ticketstop logo

05 Track record

What fintech businesses get when they work with us

Star rating on Google Play for the cashless payments app
4.8
Week delivery for fintech software platforms
10-16
Transactions processed in 3 months on a cashless payments app we built
10K+
Price agreed before work starts
Fixed

08 Why us

Why choose us?

  • 01

    Ledgers are double-entry and provable

    Transaction history and balance calculation your auditors can verify, from the first sprint.
  • 02

    Compliance is designed in, not bolted on

    KYC/AML lifecycle, transaction monitoring, and audit trails are built as features, not patched after launch.
  • 03

    License strategy in discovery, before architecture

    Money transmission licensing can take longer than the build. We put the strategy first so the timeline is honest.

09 Questions

Common questions

When your differentiation needs behavior the platform's configuration layer cannot express: a custom risk model, a multi-currency structure that does not fit its data model, or jurisdiction-specific compliance it only half covers. During discovery we scope exactly what needs to be built custom versus what stays on the platform, so you never rebuild the 80% that already works.

Double-entry accounting at the core, with every transaction balanced by construction, plus automated reconciliation matching provider events to ledger entries in real time. The ledger is designed first and tested hardest, because in fintech it is the one defect class that can end the company.

We architect so no single partner can take your product down overnight. The money-movement layer is separated from any one provider, balances are provably yours, and a migration path exists before you need it. Concentration risk is a design input, not a surprise you discover during someone else's bankruptcy.

Yes. Identity is a lifecycle: documents expire, risk classifications move, screening results change. We build event-driven reverification and real-time transaction monitoring with a triage workflow your team can actually clear, so compliance survives audits years after launch.

US money transmission can mean 40+ state licenses over 6 to 18 months, often longer than the build itself. Many products launch faster under a regulated partner's license while the direct path runs in parallel. We put the license strategy in discovery so the timeline is honest from the start.

A focused build like payment reconciliation or a digital KYC workflow runs 10 to 16 weeks ($50K to $100K). A lending platform with origination and servicing runs 10 to 16 weeks ($60K to $120K). A full fintech platform with payments, accounts, compliance, and reporting typically runs $150K to $350K, scoped after discovery. Fixed cost, agreed before development starts. Cost depends on product complexity, regulatory permissions, and third-party integrations. Compliance work is scoped explicitly, never discovered mid-build.

Yes. FCA authorization categories, Consumer Duty, operational resilience, PSD2 strong customer authentication, and GDPR for financial data are designed into the architecture during discovery. We do not give legal or compliance advice; we build what your compliance team specifies.

Get a straight answer on your fintech build.

Tell us your financial product, your regulatory permissions, and where your platform or provider is the ceiling. We will tell you whether to stay, build, or get licensed, and what it would honestly take.

  • Scope and cost agreed before work starts. No surprises. No obligation.
  • Working prototype within 3 weeks of kickoff.
  • Pay by milestone. You see progress before each invoice.
  • 60-day post-launch warranty. Bug fixes, UI tweaks, and deployment support. No retainer.
  • All conversations are NDA-protected.
Useful next steps

More on fintech