Insurance products fail in the market for operational reasons before they fail for product reasons. A policy structure your system can't model, a claims process that takes 14 days when customers expect 48 hours, and a customer portal that can't answer a status question without a call are software constraints, not business ones.
If your current platform can't handle your policy structure, or your claims team is working from spreadsheets and email threads, we build the system that actually fits how your business works.
Claims automation that cuts turnaround time and reduces manual touchpoints per claim
Policy management systems built around your product lines, not a generic insurance template
InsurTech MVPs from concept to live product in 12-16 weeks at a fixed cost
AI fraud detection and anomaly scoring built into your claims and underwriting workflows
The problem
Sound familiar?
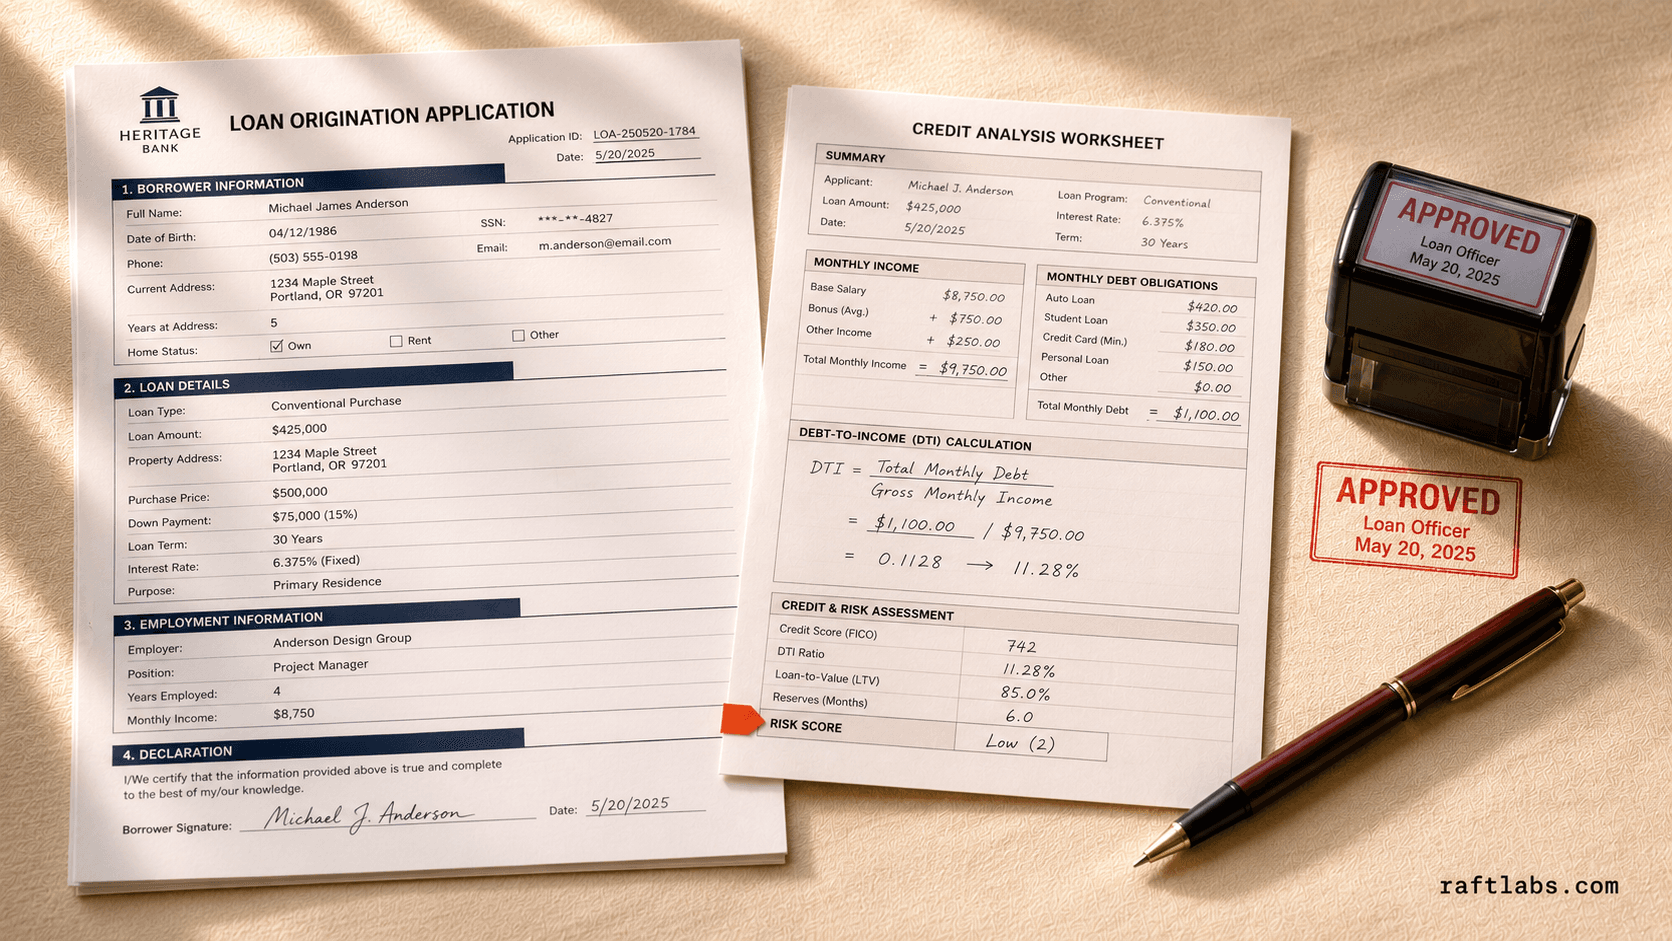
Manual claims processing adding days to your turnaround and frustrating policyholders?
Off-the-shelf platforms that can't map to your specific policy structure or product lines?
Short answer
RaftLabs builds custom insurance software: policy administration, claims automation, underwriting workbenches, and AI fraud detection for carriers, MGAs, and InsurTech teams. Compliance controls for US state DOI and NAIC rules, UK FCA requirements, GDPR, and SOC 2 are designed in from the first sprint. A focused v1 launches in 12 to 16 weeks, then grows into a full platform. We scope every project before pricing. Fixed cost, agreed before work starts.
Insurance software built around your product lines
Legacy insurance systems fail in a predictable pattern. Claims take too long because adjusters work from email chains and PDF attachments. Policy administration requires manual intervention for endorsements that should be automatic. Customer portals are so outdated that policyholders call the contact centre for things they should handle themselves. Every compliance cycle adds more manual reporting on top of a system that was never built to produce it.
We build insurance software where the operations run in the system, not around it. Policy issuance, renewals, endorsements, and cancellations are handled by software. Claims intake, routing, and status communication are handled by automation. The compliance reporting your team currently assembles by hand gets generated from data that already exists.
01 Diagnosis
Where insurance software usually breaks
01
Problem
Every policy change needs IT
Solution
Dependency on IT resources for all changes is the number one pain point insurers name about their policy administration systems. Adding a new product line or changing rating logic means IT change requests, vendor release cycles, and months of testing. Carriers and MGAs miss commercial opportunities because the policy administration system can't accommodate changes at the speed the market moves. Every new product becomes a negotiation with the system rather than a business decision. We replace the constraint with a purpose-built policy administration system that models your products the way you actually sell them. The outcome is product launches that don't need a release cycle.
02
Problem
Claims run through inboxes, not workflows
Solution
Claims arrive by email, get acknowledged manually, and get assigned to adjusters via more email. Status updates go out when someone remembers to send them. Documents attach to email chains with no version control. The audit trail for a claim is a mailbox search. Delays compound and policyholders have no visibility into where their claim stands. Every day a claim sits in an inbox costs you adjuster time, policyholder trust, and potential regulatory exposure. We build structured claims workflows that replace the inbox with a system: automated intake, adjuster queues, status communication, and a full audit trail per claim. The outcome is claims that move without the manual chase.
03
Problem
The business logic lives nowhere else on earth
Solution
Decades of accumulated logic with no documentation. Every underwriting rule added in 2003, every state-specific endorsement baked into a stored procedure: it's all in the legacy core, and often nowhere else on earth. Modernization's real cost is business logic archaeology. A carrier decides to migrate and discovers, around month eight, two dozen undocumented business rules the new platform doesn't replicate. A manual reconciliation process gets stood up temporarily. Three years later, it's still running every night. We extract the rules before we migrate, documenting what the system actually does, not what the spec says it does. The outcome is a migration that ends.
04
Problem
Agents live in five logins
Solution
An agent would have to log into separate systems - an AMS, a carrier site, a rater, a CRM, and a payment processor - to service a single client. Quote in one system, submit applications in another, check policy status by calling the carrier. When policy data changes, agents learn about it by email or not at all. Agents who find it hard to do business with you write less business with you. We build agent portals that connect directly to the policy system: real-time status, commission tracking, and quote-to-bind without the phone call. The outcome is a portal that eliminates the multi-login problem.
02 What we ship
Insurance software we build
01
Policy management systems
End-to-end policy administration covering quoting, issuance, endorsements, renewals, and cancellations. Built around your specific product lines and rating logic, not a generic insurance template you have to bend to fit your products. Includes broker and agent portals with commission tracking and real-time policy status. The outcome is product launches that don't need a release cycle.
02
Claims processing and automation
Digital claims intake with document upload, automated routing by claim type and value, and status communication to policyholders throughout the process. Workflow tools for adjusters that replace email threads with structured review queues. Settlement calculation and payment processing are integrated into the claims workflow. The outcome is adjusters spending time on judgment calls, not admin.
03
Underwriting platforms and AI risk scoring
Custom underwriting workbenches that bring structured data, document review, and decision logging into one place. AI-assisted risk scoring models process third-party data, claims history, and external signals to support underwriting decisions. Configurable rules engines handle automated acceptance within appetite and route referrals to human review. The outcome is underwriters focused on the cases that actually need them.
04
Customer portals and mobile apps
Policyholder-facing portals and mobile apps for policy documents, renewal management, claims submission, and payment handling. Designed for adoption, not compliance: intuitive enough that policyholders use them instead of calling your contact centre. Push notifications for renewal reminders, claim status updates, and payment confirmations. The outcome is contact centre volumes that fall.
05
AI fraud detection and anomaly scoring
Machine learning models trained on your claims data to flag patterns associated with fraudulent submissions. Anomaly scoring integrates into the claims intake workflow so high-risk claims get identified before they reach settlement. Outputs are explainable so your fraud team can act on the findings, not just trust a score they don't understand. The outcome is fraud caught before settlement, not after.
06
InsurTech MVPs and product incubation
For InsurTech startups and carriers launching new product lines, we take an idea from concept to a working product. Discovery, architecture, build, and launch in 12-16 weeks at a fixed cost, with scope agreed before development starts. You own the source code and the infrastructure from day one. The outcome is a live product without vendor lock-in.
03 Buy, build, or wait
The insurance software decision is usually about the legacy core: what it costs to keep, what it costs to leave, and what breaks in between.
Stay on the platform
Guidewire, Duck Creek, Applied Epic
When the system models your products and the IT dependency is manageable.
Build custom
When IT owns every change
Dependency on IT resources for all changes is the number one PAS pain point. A custom system models your products the way you sell them.
When agents live in five logins
Portals that eliminate the multi-login problem, built on your policy data.
When the logic lives nowhere else on earth
We extract the undocumented rules before migrating, so the archaeology ends.
Bottom line
Stay on the platform while it fits. Build when the core costs more than the build.
Compliance we design for, by market
United States
State DOI filing and rate-approval reporting hooks
NAIC model rules and market-conduct data trails
SOC 2 access management, audit logging, and encryption
PCI DSS scope handling where premium payments are processed
United Kingdom and Europe
FCA and PRA expectations for UK carriers and MGAs
Solvency II data and reporting requirements
GDPR data handling, residency, and DPIA support
Documented data flows for your compliance team's review
04 How we work
The compliance-first insurance build method
01
Workflow and compliance discovery
We map your current insurance operations: policy lifecycle, claims workflow, agent and broker touchpoints, and the reporting your regulators expect. We find where the manual work sits, which integrations are required, and how your actuarial and compliance teams need to interact with the platform. You get a scoped proposal and a fixed cost before any development starts. The risk this retires: the compliance requirement discovered after launch.
02
Architecture for regulated markets
Insurance software has to meet US state DOI and NAIC obligations, UK FCA rules, GDPR, or Solvency II depending on your markets. We design the data model, access controls, audit logging, and infrastructure to meet those obligations before we write code. Your compliance team reviews the architecture document before the build begins. The risk this retires: the control the regulator asks about that the system can't produce.
03
Sprint-based build with fortnightly reviews
We build in two-week sprints. You see working software at each review, the real system, not a prototype. Adjusters, underwriters, and agents test each feature as it ships and give feedback before the next sprint. This avoids the common failure mode where a large insurance platform gets built to a spec nobody validated against real users. The risk this retires: the platform nobody validated until go-live.
04
Testing, launch, and handover
Before go-live, we run user acceptance testing with your adjusters, agents, underwriters, and compliance staff. We provide training, run onboarding sessions, and support the production launch. You own the source code and infrastructure. Post-launch support is available for the period after launch. The risk this retires: the migration where the numbers don't agree and nobody knows why.
Trusted by
05 Track record
What a first build looks like
01
Founded
2015
02
Weeks for a focused insurance v1
12-16
03
Cost, agreed before we build
Fixed
We have not shipped a named insurance platform we can publish yet, so we will not dress up an unrelated build as one. The closest documented proof is the high-volume OCR document pipeline below. The extraction, validation, and offline-sync approach it uses on retail transaction data is the same one a claims-document or policy-application intake pipeline runs on.
Across dozens of industries, we recognise your situation fast, then frame the fix around your margin and your operations, not a generic template.
02
We own the number, not the ticket
We measure success the way you do: hours saved, revenue earned, margin recovered. We stay through launch and growth, so the result is ours to own.
03
Serious businesses trust us
Vodafone, T-Mobile, Cisco, Energia, Aldi, Nike. Building since 2015. Serious businesses keep coming back because we stay accountable long after launch.
09 Questions
Common questions
Insurance software development covers building the systems that run insurance operations: policy administration, claims processing, underwriting tools, customer portals, broker portals, and the data infrastructure connecting them. For InsurTech companies, it often means building a new platform from scratch. For established carriers, it usually means replacing or extending a legacy core system with modern digital workflows. The distinguishing factor in insurance is the data model. Policies, endorsements, claims, coverages, limits, and exclusions are specific enough that teams without insurance domain knowledge build it wrong. They only discover the problem when they try to handle edge cases in production.
We build the technical controls each regime expects. Encryption at rest and in transit. Role-based access with minimum-necessary permissions. Audit logging of every access and change to sensitive data. Data residency configuration where regulations require it. Documented data flows for your compliance team's review. For US carriers that means the reporting hooks state DOI filings and NAIC model rules depend on. For UK and EU teams it means building to FCA and PRA expectations and Solvency II data requirements. We don't give regulatory or legal advice. Only your compliance and legal team can assess whether your product meets its obligations. What we do is build the technical foundation that makes compliance achievable and give your team the documentation they need. We've supported clients through FCA technical reviews and GDPR data protection impact assessments with architecture documentation and technical answers for their advisors.
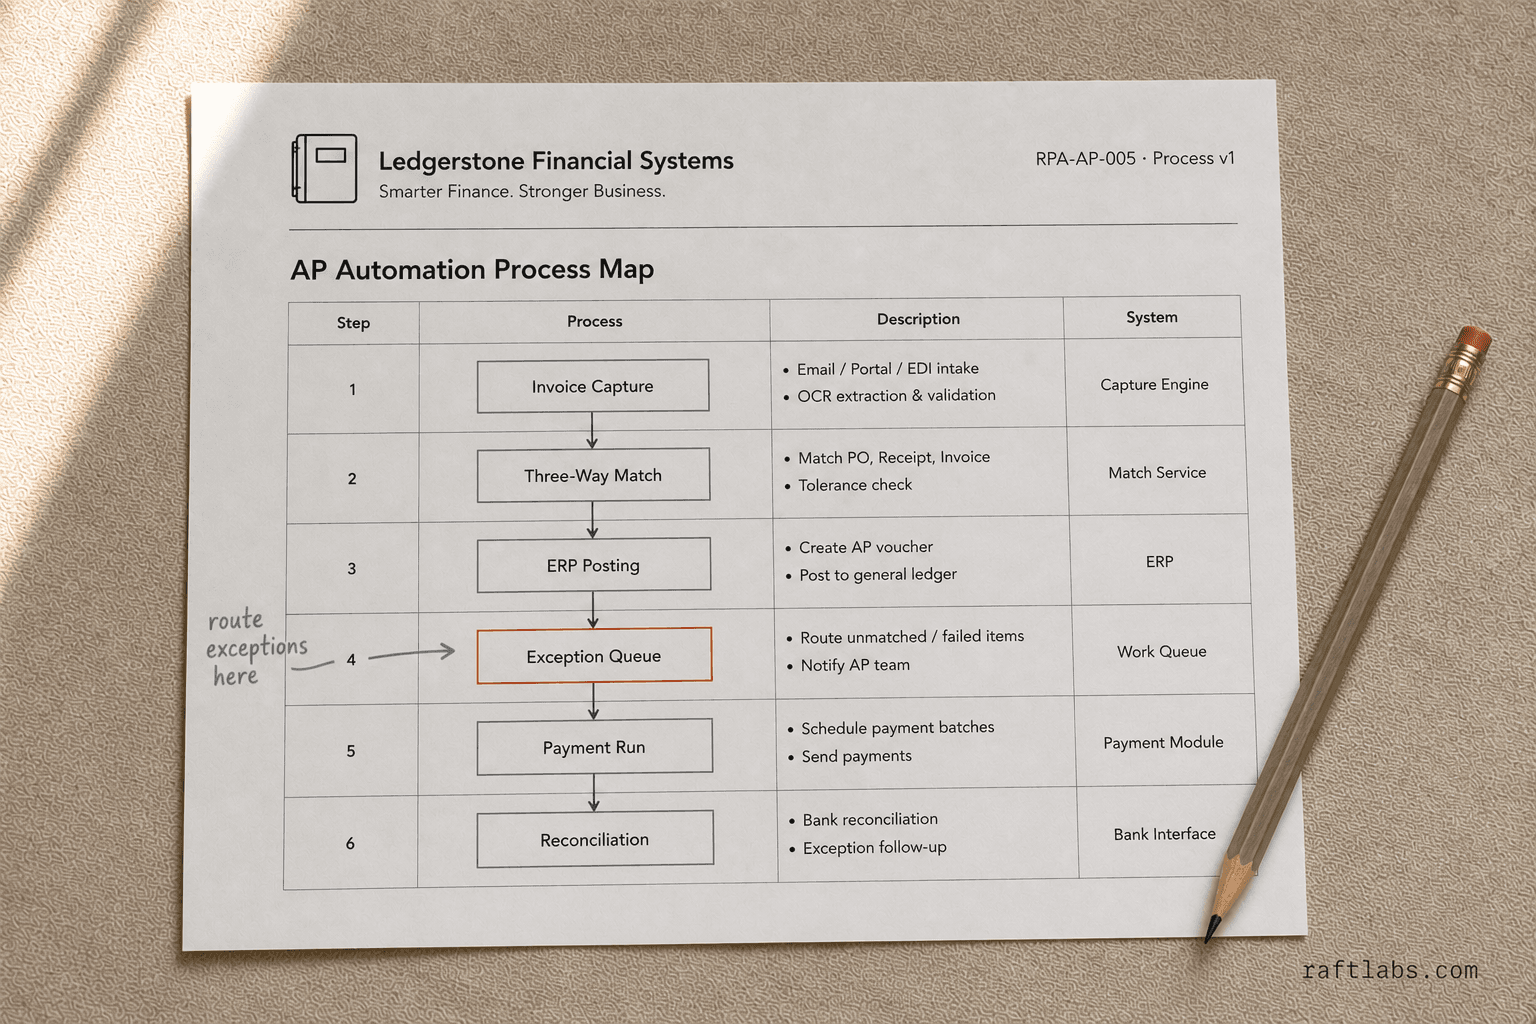
Claims automation starts with a clear map of your current claims workflow: every step, every decision point, every person who touches a claim. We identify which steps have clear rules that software can run and which genuinely need human judgment. Straightforward claims within clear parameters with complete documentation go through automated routing, assessment against your rules, and settlement without adjuster involvement. Complex or ambiguous claims route to an adjuster with all the relevant data already assembled. The result is that your adjusters spend their time on claims that actually need them, not on admin that a system should handle.
A focused first slice, a digital claims portal, a quote-and-buy flow for a single product line, or an underwriting workbench, launches as a validated v1 in 12-16 weeks. We scope every project before pricing: fixed cost agreed upfront, no hourly billing, no scope-creep invoices at the end. The full platform grows from there as you add product lines. The timeline depends on how many external integrations you need and how complex your rating and eligibility logic is. We scope it in detail before development starts, so you know what you are getting and by when.
Machine-augmented underwriting is the design: the system handles data gathering, document review, and risk scoring, then routes the decision to a human with everything assembled. Underwriters focus on the cases that actually need them instead of the admin that fills their day. Nobody's judgment gets replaced; the busywork around it gets automated.
Get a build-vs-keep plan for your insurance operation
Tell us what you're building, which product lines it covers, and your compliance requirements. We'll tell you how we'd approach it and what it takes to ship.
Scope and cost agreed before work starts. No surprises. No obligation.
Working prototype within 3 weeks of kickoff.
Pay by milestone. You see progress before each invoice.
60-day post-launch warranty. Bug fixes, UI tweaks, and deployment support. No retainer.