LendingTech and BNPL Software Development

Digital lenders, BNPL operators, SME lending platforms, and credit unions whose credit product, underwriting logic, or collections workflow has outgrown what off-the-shelf loan management systems can configure. When your credit policy, embedded lending model, or regulatory obligations require behaviour a standard platform cannot express without significant compromise, we build the lending system around your actual product.

  • Loan origination systems with application intake, bureau integration, and a credit decisioning engine built to your specific credit policy

  • BNPL platforms with real-time underwriting, merchant dashboard, repayment scheduling, and embedded checkout integration

  • Loan servicing software covering repayment management, arrears workflows, early settlement, and collections queues

  • Regulatory compliance built into the architecture from day one, not retrofitted before audit

The problem

Sound familiar?

  • Credit analysts spending days on each application because the underwriting system pulls bureau data but can't apply your actual credit policy automatically?

  • BNPL checkout conversion dropping because your risk decisioning takes too long and competitors approve customers in seconds?

  • Loan servicing running across three disconnected tools so collections, repayments, and arrears management never reconcile without manual work?

Short answer

RaftLabs builds custom lending software for digital lenders, BNPL platforms, SME lenders, online mortgage companies, and credit unions. Our lending software development work covers loan origination systems, automated credit decisioning engines, underwriting workflow tools, loan servicing platforms, and collections management. Most lending software projects deliver in 12 to 16 weeks at a fixed, agreed cost.

01 Diagnosis

Problems we solve for lenders and BNPL operators

  1. 01
    Problem

    Your underwriting team reviews every application manually because there is no decision engine

    Solution

    When each credit application lands in a shared inbox and an analyst pulls bureau data, checks affordability from bank statements, and applies policy rules by hand, throughput is capped at the number of analysts you have. Decision quality varies depending on who reviews the file. Applications that should take minutes sit in queue for two to four days. As volume grows, the bottleneck tightens before it breaks.An automated credit decisioning engine applies your policy consistently to every application. Applications within your automated appetite get an instant decision. Applications outside it go to a referral queue with the relevant data pre-populated, so analyst time focuses on genuine edge cases rather than data assembly.

  2. 02
    Problem

    BNPL checkout conversion is losing ground because credit decisions are too slow

    Solution

    At the point of checkout, a customer who waits more than a few seconds for a credit decision abandons the cart. If your BNPL underwriting calls a bureau, runs an affordability check, and waits for a manual review trigger before returning a decision, the latency is visible and the conversion cost is real. Competitors using real-time decision engines approve customers in under two seconds.Real-time underwriting that pre-fetches bureau data, runs your credit policy against the result, and returns a decision in milliseconds converts the checkout interaction from a friction point into a feature. Merchant dashboards show approval rates, basket sizes, and repayment performance by product category so you can tune policy without guessing.

  3. 03
    Problem

    Loan servicing runs across disconnected tools so arrears and repayments never reconcile cleanly

    Solution

    When origination lives in one system, repayment collection in a payment gateway, and arrears management in a spreadsheet, reconciling the three is a weekly manual exercise. Payments that fail in the gateway take days to surface as arrears. Collections teams work off data that is always a step behind. Regulatory reporting pulls from all three sources and never agrees.A single loan servicing platform that holds the loan record, schedules repayments, receives payment confirmation events in real time, and triggers arrears workflows automatically means your operations team works from one source of truth. Failed payment retry logic, collections escalation rules, and customer communications run without manual intervention.

  4. 04
    Problem

    Credit policy changes require developer tickets because the rules are hardcoded in the system

    Solution

    When the credit policy lives inside application code rather than a configurable rule engine, every policy adjustment needs a code change, a test cycle, and a deployment. Changing a score threshold, adding an income verification step, or excluding a borrower category becomes an engineering ticket. A policy change that should take a credit risk manager an afternoon takes three weeks and ties up engineering capacity.A rules-based decision engine with a UI your credit team can operate means policy changes deploy in hours. Full audit trails on rule versions, with the decision log showing which policy version approved or declined each application, give your compliance team the documentation they need without a support ticket.

02 What we ship

Lending software we build

  1. Loan origination systems

    Application intake covers digital borrower onboarding, document upload, identity verification via providers like Onfido or Persona, and pre-population of bureau data from Experian, Equifax, or TransUnion so your underwriters are not re-keying data. A structured application workflow routes each file through the steps your credit policy requires before it reaches decisioning.

    The credit decisioning engine applies your specific underwriting rules, not a template. Income verification, affordability calculation using open banking data from Plaid or TrueLayer, debt-to-income thresholds, and custom scoring variables are all configurable by your credit risk team without code changes. Decisions within your automated appetite return in seconds.

    Built for consumer lenders replacing manual intake queues, SME lenders building a digital origination channel, and specialist lenders whose product mix requires a decisioning engine that a standard LOS cannot configure.

  2. BNPL platforms

    Embedded checkout integration gives merchants a single SDK or API to add BNPL as a payment option, with a branded experience that keeps the customer on the merchant's checkout. Real-time credit decisioning returns an approval or soft decline in under two seconds, so cart abandonment from underwriting latency is not a factor.

    Repayment scheduling handles instalment plans, automated payment collection via Stripe or Dwolla, failed payment retry logic, and customer-facing repayment management. The merchant dashboard surfaces approval rates, average order values, and repayment performance by category so your risk team has the data to tune policy.

    Built for BNPL operators building a credit product from scratch, retailers adding BNPL to their checkout, and embedded finance businesses adding short-term credit to an existing payment product.

  3. Automated underwriting and credit decisioning

    A configurable rules engine applies your credit policy as a sequence of decision gates: bureau score threshold, income verification, affordability ratio, fraud flags from providers like Socure or Sardine, and any custom variables your model uses. Policy rules are managed through a UI your credit risk team operates directly, with version control and a full audit trail on each change.

    AI-assisted underwriting uses machine learning models trained on your historical loan performance data to surface risk signals that static rule sets miss: thin-file borrowers who perform well, application patterns that correlate with early arrears. The model augments the rules engine rather than replacing it, so your credit team stays in control of policy.

    Built for lenders replacing manual underwriting, BNPL operators improving approval rates without increasing default rates, and credit unions building a data-driven decisioning capability.

  4. Loan servicing platforms

    The loan ledger holds every loan record with disbursement date, principal balance, interest accrual, scheduled repayment dates, and payment history. Repayment collection integrates with ACH, Dwolla, or Stripe, with real-time payment confirmation events updating the loan record so the balance is always current.

    Arrears management applies configurable rules to overdue accounts: automated payment retry, SMS and email contact sequences via Twilio, internal escalation to a collections queue at defined days past due, and external collections handoff workflows. Early settlement calculations and loan modification workflows handle the edge cases that generate the most manual work in a growing book.

    Built for consumer and SME lenders whose current servicing tools require manual reconciliation, BNPL operators scaling repayment volume beyond what a spreadsheet supports, and mortgage lenders who need a servicing platform that reflects their product structure.
  5. Collections management software

    Collections workflow automation segments overdue accounts by days past due, balance, risk tier, and contact preference, then routes each account to the right next step: automated payment retry, outbound SMS or email, agent-led contact, or external debt collection agency referral. Each step is logged with timestamp and outcome so your compliance team has a full contact history.

    Agent workload management gives your collections team a prioritised daily queue rather than a raw list of delinquent accounts. Predictive prioritisation uses repayment history and behavioural signals to surface accounts most likely to respond to contact on a given day, so agents spend time on accounts where contact makes a difference.

    Built for lenders whose collections team works from spreadsheets and manual queues, BNPL operators facing rising arrears as their book scales, and credit unions adding a digital collections workflow to replace their current paper-based process.

  6. Regulatory reporting and compliance infrastructure

    ECOA adverse action notice generation creates compliant decline letters with the specific reasons required under US consumer lending law, pulling directly from the decisioning engine's output so the reason codes are accurate and traceable. HMDA data capture records the required fields at application and decision stage so your annual LAR submission is not a manual data assembly exercise.

    Audit trails on every credit decision, policy rule change, and customer interaction give your compliance team the documentation for a regulatory examination without a support ticket. For UK lenders, FCA Consumer Credit Act compliance includes responsible lending assessment records and Section 75 liability documentation. Data retention rules under GDPR are enforced at the data layer, not by manual deletion processes.

    Built for regulated lenders who need compliance infrastructure that scales with volume, BNPL operators preparing for FCA authorisation under the UK's 2026 BNPL regulatory framework, and credit unions whose current audit trail is a spreadsheet.

03 Buy, build, or wait

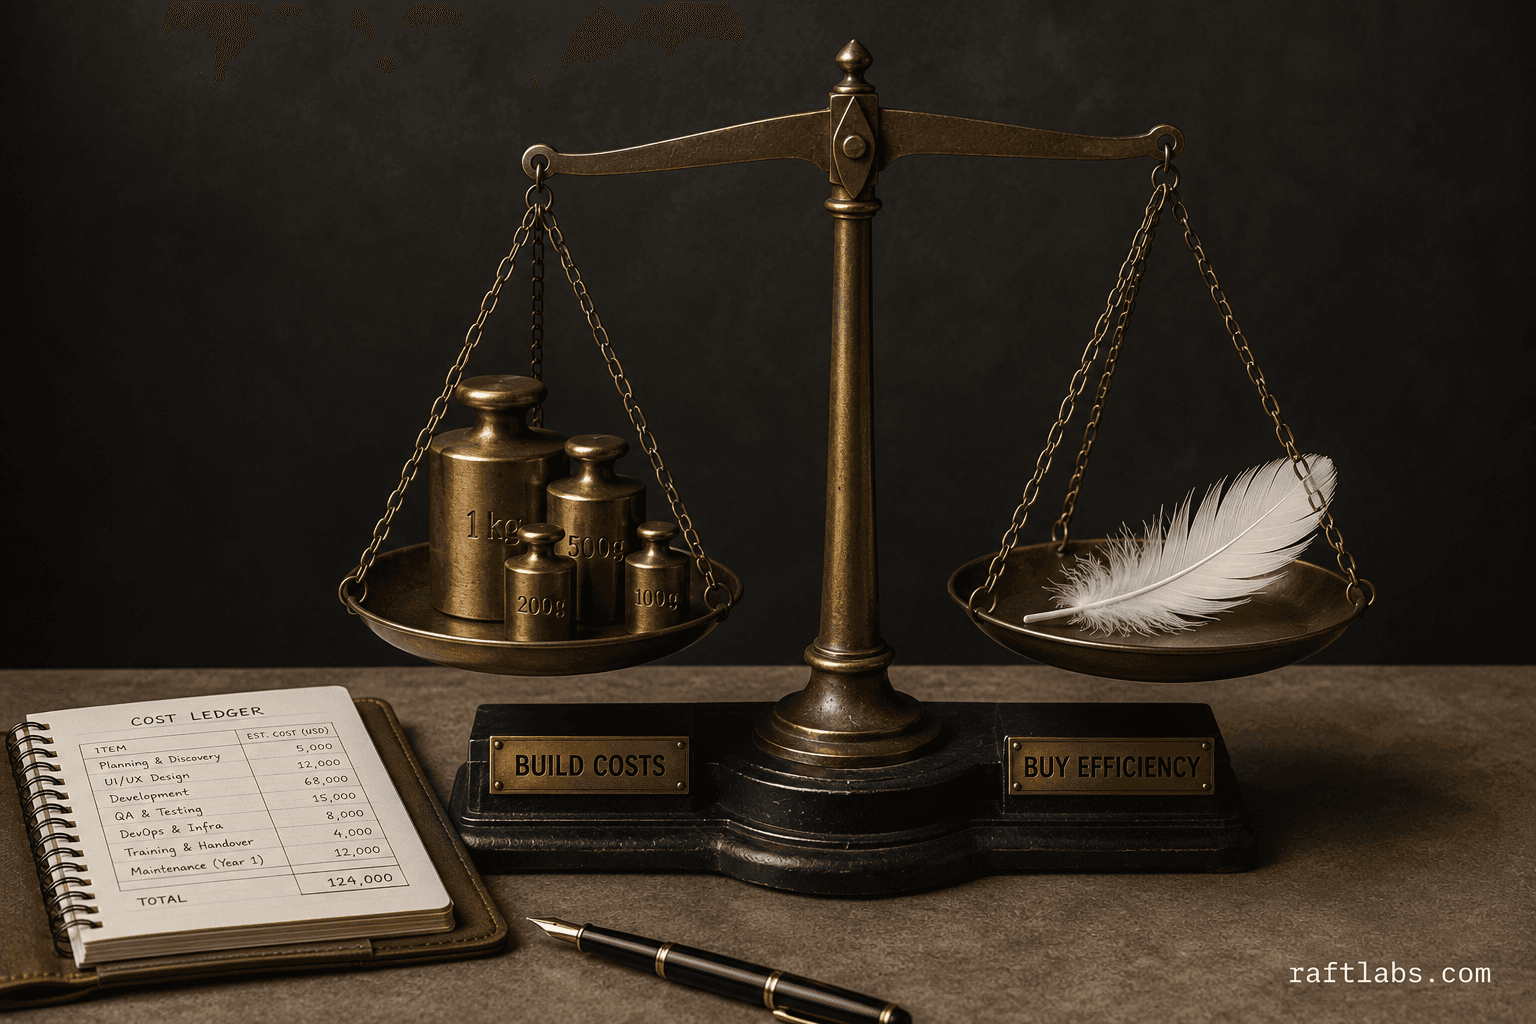
The lending software question is really about whether your credit product is standard enough to configure, or specific enough to build.

Buy or rent

  • A loan management platform, for standard products

    Straightforward term loans or BNPL where the platform's decisioning and servicing fit your credit policy without heavy customization.

  • Wait, while the book is small

    Early volumes where manual underwriting still works and the platform fees are cheaper than a build.

Build custom

  • When the credit policy is the product

    Proprietary scoring, sector-specific underwriting, or embedded lending where the decisioning logic no platform expresses natively.

  • When compliance is structural

    Adverse action workflows, HMDA capture, audit trails on every decision. Built into the architecture, not bolted on before audit.

  • When servicing is the margin

    Collections queues, arrears workflows, and repayment scheduling tuned to how your team actually recovers.

Bottom line

Stay on the platform while the credit product is standard and volumes are small. Build when the underwriting logic, the compliance architecture, or the servicing workflow is the differentiator.

04 How we work

How we build lending software

  1. 01

    Discovery

    We map your credit product, the lending workflow from application to collections, the regulatory permissions you hold, and the integrations your system needs: credit bureaus, open banking providers, payment rails, and any existing core banking or CRM systems. We document where your current approach creates credit risk, compliance gaps, or operational bottlenecks. A fixed-price specification is produced before any code is written.
  2. 02

    Architecture

    We design the data model around your specific lending product: the loan record structure, the decisioning engine rule schema, the repayment ledger design, the audit trail requirements, and the API surface your front-end and third-party integrations will use. Compliance requirements, ECOA adverse action workflows, HMDA capture points, or FCA responsible lending assessment fields, are all factored into the architecture before a line of code is written.
  3. 03

    Build

    Two-week sprints with working software at each checkpoint. The credit decisioning engine and loan origination flow ship first so your credit team can validate policy rules against real applications early. Servicing, collections, and regulatory reporting follow in subsequent sprints. Integration with bureau providers, open banking APIs, and payment rails are built and tested in a sandbox environment before production go-live.
  4. 04

    Launch and support

    Phased go-live starting with a controlled borrower cohort before full launch. Monitoring covers decisioning latency, payment failure rates, arrears triggers, and compliance exception flags. Post-launch support handles regulatory changes, credit policy updates, and product iterations as your loan book grows.

Trusted by

Perceptional logo
Musgrave Group
UrShipper logo
Brux Dental Solutions
Bella Skin Institute Logo
Energia Rewards
Draftly logo
TuneClub Logo
Sekou LMS logo
Logo of food order management app gula
SnelwegDeals
Grubly logo
PSi logo
Instantor Rewards logo
logo of Mobile app for events, membership clubs, and communities
AldiFest retail campaign logo
Vidmattic logo
EMS Connect logo
Worx Squad logo
logo of Online Web App For Making Intro
logo of Referral and Viral Marketing Platform
Concurrences logo
GE logo
Ticketstop logo

05 Track record

What lending businesses get when they work with us

Fintech and financial services businesses served across the US, UK, and Australia
15+
Week delivery for lending and BNPL software platforms
12-16
Software products shipped across fintech, banking, and payments
100+
Cost delivery agreed before development starts
Fixed

08 Why us

Why choose us?

  • 01

    We've seen your problem before

    Across dozens of industries, we recognise your situation fast, then frame the fix around your margin and your operations, not a generic template.
  • 02

    We own the number, not the ticket

    We measure success the way you do: hours saved, revenue earned, margin recovered. We stay through launch and growth, so the result is ours to own.
  • 03

    Serious businesses trust us

    Vodafone, T-Mobile, Cisco, Energia, Aldi, Nike. Building since 2015. Serious businesses keep coming back because we stay accountable long after launch.

09 Questions

Common questions

Yes. We build loan origination systems where the underwriting decision engine applies your specific credit policy, not a template. That includes configuring the rule sets, data inputs from credit bureaus like Experian, Equifax, or TransUnion, open banking affordability data from Plaid or TrueLayer, and any proprietary scoring variables your credit team uses. The output is consistent automated decisions for applications within your automated appetite, with a referral queue for edge cases that genuinely need analyst review.

A production-grade BNPL platform with real-time credit decisioning, merchant integration, repayment scheduling, and basic compliance typically takes 14 to 20 weeks with our team. That timeline covers discovery, architecture, build, and go-live with a controlled merchant cohort. A simpler embedded lending MVP with fewer merchant integrations can deliver in 10 to 12 weeks. We scope the timeline precisely during discovery before any cost is agreed.

A focused build, such as a loan origination system or a BNPL underwriting engine, is scoped around the credit product, the bureau and open banking integrations, and compliance requirements. A full lending platform covering origination, servicing, collections, and regulatory reporting is scoped the same way. Cost is agreed and fixed before development starts.

Yes. We integrate with Experian, Equifax, TransUnion, and specialist bureau providers. For open banking affordability assessment we work with Plaid, TrueLayer, MX, and Finicity. Payment disbursement and repayment collection connects to Stripe, Dwolla, Moov, and ACH rails depending on your market. We map the integration landscape during discovery and build each connection to your specific data and decisioning requirements.

Compliance requirements are factored into the system architecture during discovery, not added afterwards. For US lenders that means ECOA adverse action notice workflows, HMDA reporting data capture, state-level disclosure rules baked into loan document generation, and full audit trails on every credit decision. For UK lenders we address FCA Consumer Credit Act obligations, responsible lending assessments, and GDPR data retention. We do not provide legal advice, but we build systems designed to meet the compliance obligations your legal team specifies.

Yes. Building the differentiated layer on top of or alongside an existing loan management system, the custom risk model, proprietary scoring logic, or collections workflow the platform cannot configure, is a specific type of engagement we take on. We scope exactly what needs to be built custom versus what stays on the platform during discovery, so you are not paying to rebuild what already works.

Building the automation business case? Run your own numbers with our automation ROI calculator before the call.

Get a build-vs-buy plan for your lending team.

Tell us what you are building and we will scope it out together.

  • Scope and cost agreed before work starts. No surprises. No obligation.
  • Working prototype within 3 weeks of kickoff.
  • Pay by milestone. You see progress before each invoice.
  • 60-day post-launch warranty. Bug fixes, UI tweaks, and deployment support. No retainer.
  • All conversations are NDA-protected.

Useful next steps

More on fintech