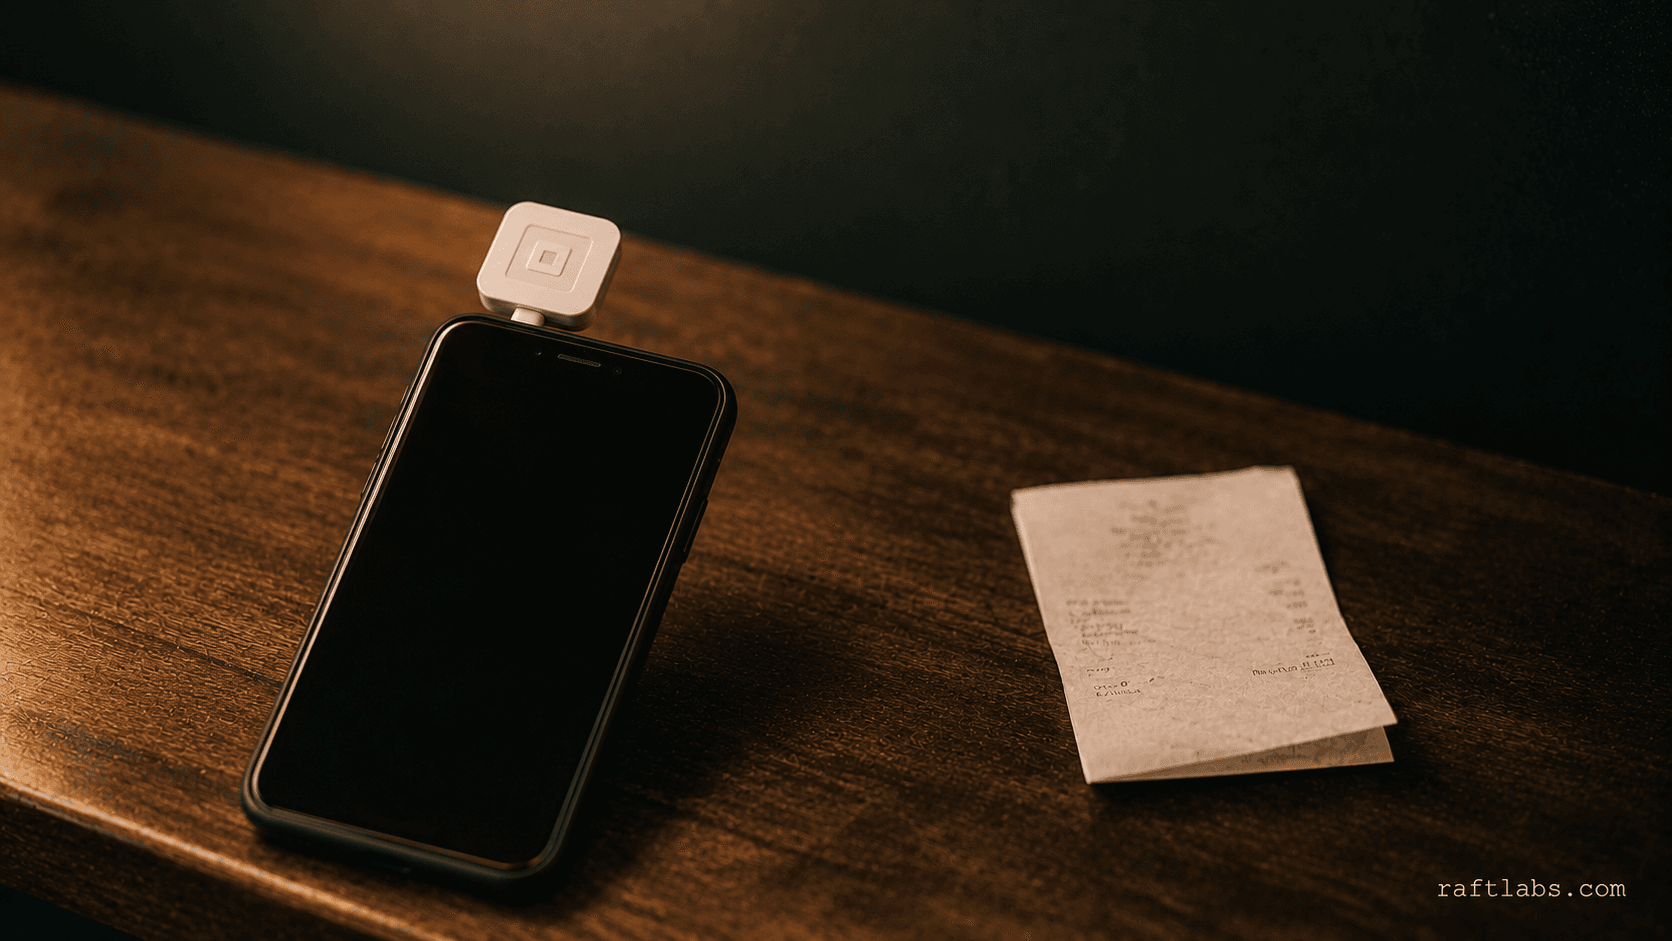
Mobile PoS and merchant-acquiring platform for a UAE fintech operator
Stripe and PayBy running behind one transaction ledger for a UAE fintech operator.
Payment Processing Software Development
A direct payment gateway integration handles the transaction itself well: authorisation, capture, refund. Custom payment software is the right choice when you need the layer above the gateway, the transaction routing logic, the multi-currency ledger, the reconciliation system, the merchant settlement workflow, and the fraud controls that turn a payment API into a payment product. We build payment platforms for marketplaces splitting payments between buyers and sellers, fintech products embedding payments, and businesses replacing manual reconciliation with an automated system.
Payment gateway integrations with Stripe, Adyen, Braintree, and direct acquirers with multi-provider routing
Custom checkout flows with 3D Secure 2.0, tokenised card-on-file, and PCI scope reduction
Multi-currency processing with real-time FX rates and local payment method routing
Automated reconciliation, marketplace split payments, and merchant settlement
Bring the problem, the current workflow, or the existing code. We reply with a practical next step within one business day.
Trusted by



The brief
Good software decisions begin with the constraint, not a list of features or a preferred technology.
Reconciliation team spending hours each day manually matching gateway transactions against bank statements because there's no automated matching system?
Running a marketplace where split payments, seller payouts, and reconciliation still require manual spreadsheet work?
Plain answer
RaftLabs builds custom payment processing software for fintech companies, marketplaces, and financial institutions who need payment gateway integrations, multi-currency transaction processing, automated reconciliation, fraud controls, and merchant or seller settlement built around their specific payment model. We scope every project before pricing and deliver at a fixed cost.
What to remember
Every morning the finance team opened three tabs: the bank statement, the gateway settlement report, and the internal ledger. Then they matched rows by hand, one transaction at a time, chasing the handful that didn't line up.
By the time the numbers agreed, half the day was gone. And the mismatch that actually mattered, the one worth investigating, was buried under a hundred that were just FX rounding.
A payment platform doesn't ask the team to find the exception. It clears the matches on its own and puts the exception at the top of a queue, with the bank entry and the nearest settlement record side by side.
The gateway moved the money. Everything above it is the product.
A direct payment gateway integration handles the transaction itself: the card authorisation, the capture, the refund. The product starts above that layer. Transactions route between multiple providers for redundancy. Funds from different transaction types separate in the ledger. Platform fees deduct before merchant settlement, and failed transactions retry and surface their failure reason. These are product decisions the gateway's SDK doesn't make for you.
Payments is now a multi-trillion-dollar layer of the economy. McKinsey's Global Payments Report puts annual global payments revenue above $2 trillion, and the businesses building on top of it increasingly route across several processors, currencies, and settlement models that no single gateway SDK was built to handle. The moment a platform splits a payment, settles to more than one party, or reconciles across providers, the logic moves out of the gateway and into software you own.
Three layers get confused in most briefs. Naming them keeps scope honest.
We build the orchestration layer for marketplaces managing split payments, fintech platforms embedding payments into a non-financial product, subscription businesses managing recurring billing with dunning management, and businesses replacing manual reconciliation with an automated system.
RaftLabs has been shipping production software since 2015, with a track record building payment, marketplace, and fintech platforms. One team scopes the payment flows and builds the platform, production-grade, compliant, and reliable from day one. No offshore handoff after the contract is signed.
Everything on the left should already be true for your operation. Even one thing on the right, and a direct Stripe or Adyen integration is the smarter first step.
A marketplace, platform, or fintech product that splits payments, deducts a platform fee, or settles to multiple sellers.
Multi-provider routing, multi-currency settlement, or a transaction volume where automated reconciliation saves more than it costs to build.
Real flow complexity above the gateway: a currency ledger, retry logic, or fraud controls your processor's SDK doesn't cover.
A single currency, a single payment method, and no multi-party settlement, where a direct Stripe or Adyen integration already covers you.
Low transaction volume where matching by hand still costs less than automating it.
A standard checkout with no routing, ledger, or settlement logic beyond the gateway.
Scope
Integration with your acquiring layer, Stripe, Adyen, Checkout.com, or Braintree, via SDK or REST API for payment intent creation, capture, refund, and webhook delivery. Multi-provider routing is a configurable rule engine, by card BIN range, transaction amount, currency, or MCC, with automatic failover to a secondary processor. Every payment intent call carries an idempotency key so network retries do not duplicate a charge; webhook events are HMAC-SHA256 verified before updating order state.
One-click checkout for returning customers via tokenised card-on-file; guest checkout for new customers with no forced account creation. 3D Secure 2.0 integrates for PSD2 strong customer authentication, with dynamic triggering that exempts low-risk transactions from friction under the TRA exemption. Card fields are processor-hosted, Stripe Elements or Adyen Drop-in, so raw card data stays off your application, keeping PCI scope tight.
Live FX rates from ECB reference feeds or a commercial provider, with configurable spread over mid-market. A multi-currency ledger tracks each currency balance separately; settlement conversion applies at transaction time or deferred to the daily batch depending on your FX exposure preference. Local payment method routing extends beyond card by market: iDEAL, SEPA, BACS, UPI, Pix, OXXO, each with its own settlement timeline and refund mechanics.
A reconciliation engine matches incoming bank statement transactions against gateway settlement reports and the internal ledger, marking matched items reconciled without manual intervention. An exception queue shows the bank entry, the nearest matching settlement record, and the discrepancy, rather than requiring the team to find it themselves. Tolerance handling auto-clears low-value FX-rounding discrepancies; a daily reconciliation report shows the reconciled and unreconciled position across all methods and currencies.
Built on Stripe Connect or Adyen Platforms depending on your payout model, PayFac (you as merchant of record) or aggregation (sellers onboard directly). Seller KYC and bank verification complete before first payout. Commission deduction, reserve holds against chargebacks, and automated payout scheduling are configurable per seller tier. Settlement statements show each merchant their transactions, fees, and net payout; chargeback management deducts disputes from the next settlement automatically.
Velocity controls limit transaction count and value per card, account, IP, and device within a rolling window. Rule-based screening and third-party fraud scoring (Stripe Radar, Sift, Kount, Sardine) combine IP reputation, device fingerprinting, and behavioural signals into a risk score that drives approve, decline, or manual-review routing. Dispute-rate monitoring alerts before your chargeback ratio approaches the card network's compliance threshold: Visa flags merchants at a 0.9% dispute ratio under VDMP, Mastercard at 1.5% under its Excessive Chargeback programme (card-network rules, 2024). Cross that line and you face per-dispute fines and, eventually, loss of acquiring, so the monitoring should warn early, not report after the fact.
Plan management defines billing cycle, price, currency, and trial period per product. A recurring billing engine processes renewals automatically, handling the payment attempt and triggering the next cycle or the dunning sequence on failure. Dunning runs a configurable retry sequence with subscriber communication; upgrade and downgrade handling computes proration automatically. Subscription lifecycle events publish to a webhook for downstream systems.
Payment software fails in specific, repeatable ways. Naming them up front is how you know we have shipped this before, not just read the docs.
Proof
RaftLabs has shipped software since 2015 across AI, SaaS, mobile, automation, and enterprise platforms.
A UAE fintech operator came to us to replace hardware card terminals with a mobile app. Merchants now take contactless cards, QR codes, tap-to-pay, and payment links from a phone. Two payment processors, PayBy and Stripe, run behind a single transaction ledger. Card details are encrypted in the backend; no full card number is stored. This is the assess-then-rebuild path for a payment MVP that has outgrown a single processor or cannot yet meet compliance and scale. Read the full case study.
Tell us your payment model, the currencies, the gateways, and where the current process relies on manual reconciliation. We'll scope a payment platform built around your actual transaction flows.
How it works
We map your transaction flows, settlement model, and processor requirements, and you leave with a written scope document and a fixed-price quote.
Ledger structure, routing rules, and PCI scope-reduction approach are designed and confirmed against your processor stack before development starts, so the scope matches the processors you actually use.
Gateway integration, checkout, reconciliation, and settlement are built in parallel and tested against processor sandboxes throughout, so integration risk surfaces early.
Production launch happens only after the reconciliation engine is validated against real settlement files.
Proof
Stripe and PayBy running behind one transaction ledger for a UAE fintech operator.
Two-way POS sync, AI invoice scanning, and inventory rules for a multi-site US operator.
IntroJoy removes the back-and-forth from warm professional introductions. Both parties confirm via double opt-in email, the connector is done after drafting once, and professional networks grew 20% for active users.
Scope decides where you land, not negotiation:
What it costs
Gateway integrations, a multi-currency ledger, reconciliation automation, and the settlement and fraud controls your payment model needs.
The largest cost variables are the number of acquiring integrations, marketplace payout complexity, and reconciliation depth. Start with the core flow, add complexity once it's live and processing real transactions.
Starting investment
Scoped per project
Start with the core gateway integration and ledger, then add reconciliation depth and fraud controls as volume grows.
No hourly billing
Once we scope your first phase, that price is locked in writing. No hourly billing, no surprise invoices for work outside the agreed scope.
Validated before go-live
The reconciliation engine is validated against your real settlement files before launch, so the numbers agree on day one, not week three.
Payment software rarely stands alone. Related build work includes fintech automation for KYC, reconciliation, and fraud workflows, AI for fintech for transaction scoring and anomaly detection, and business process automation for the settlement and back-office steps around a payment platform. For the wider track record, see our fintech software work.
Work with us
Bring the rough workflow, half-built product, or messy brief. We will map the smallest useful first move, then send scope, timeline, and price in plain English.
A direct Stripe or Adyen integration is the right choice for a straightforward payment model: a single currency, a single payment method, no multi-party settlement. Custom becomes right when the flows are more complex: a marketplace splitting payments between buyers and sellers, a platform deducting a fee before settling to merchants, multi-provider routing with automatic failover, a multi-currency product requiring a currency ledger, or a business whose volume has reached the point where automated reconciliation saves more than the cost of building it.
PCI DSS applies to any business that stores, processes, or transmits cardholder data. Most payment platforms reduce the audit burden through scope reduction: processor-hosted card fields (Stripe Elements, Adyen Drop-in, Braintree Hosted Fields) mean raw card data never touches your servers. Tokenisation for card-on-file stores a processor-generated token. We build with scope reduction as a design principle from the start: no card data in your database, logs, or error reporting. Your QSA makes the final scope call.
Yes. Live FX rate feeds (ECB reference rates or a provider like Open Exchange Rates) power local-currency pricing at checkout. Local payment methods extend beyond card: iDEAL for the Netherlands, SEPA for Europe, BACS for the UK, UPI for India, Pix for Brazil, OXXO for Mexico. FX conversion can happen at transaction time (rate locked at checkout) or settlement time (deferred cost, simpler reconciliation). We scope the currency list, market list, and payment rails during discovery and confirm processor coverage before development starts.
Yes. Common integrations cover Xero, QuickBooks, Sage, and NetSuite. The integration posts each settled transaction or settlement batch to the correct nominal code, reconciles the payment platform's ledger against the accounting system's bank account, and flags discrepancies for investigation. For a custom general ledger or ERP, we build the integration using the available API or file-based exchange.
The fog is the feature. The diagnostic ritual: what specific services does the PCI fee cover? Scan frequency and who runs them? SAQ help? Breach protection included? The never-touch-card-data principle is the single biggest cost reducer: a third-party gateway or hosted checkout means card data never touches your server, so PCI DSS on your own stack is not required. A custom checkout touching raw card data explodes scope. Since 2025, PCI DSS requirement 6.4.3 (payment-page script inventory) and 11.6.1 (tamper detection) are mandatory.
Transparent pricing equals true cost plus markup shown separately. Flat-rate simplicity costs you at volume; interchange-plus usually wins as volume grows. Watch the stack: monthly and annual fees, per-transaction markups, and multi-year terms with early-termination penalties. Same-day and next-day funding is advertised: ask who withholds what. Running multiple processors is common: a primary plus PayPal for buyer trust; consolidate transaction data into one CRM.
The goal is not an unbeatable system. Make fraud cost more than it is worth so attackers go elsewhere. Scalable fraud matters more than targeted attacks. Apply friction only to the un-scannable few; keep it smooth for the many. Gateway equals the front door: it captures and encrypts. Processor equals the plumbing: it moves the money. Modern platforms bundle both; the distinction mainly matters with standalone gateways plus a separate merchant account. Multi-provider routing exists so one processor's outage is not your outage.
Four rituals. One: the PCI-fee question. What specific services does the fee cover? Two: the card-data question. Does card data ever touch our server? Three: the fee-honesty question. True cost plus markup, or flat rate hiding margin? Four: the payout question. How fast do we get paid, and who withholds what? When does a business need custom payment software instead of using Stripe directly? When routing, reconciliation, marketplace settlement, or provider redundancy matter more than checkout alone. The reconciliation that used to take until lunch: that is the outcome to verify.
Scope decides the price. A payment platform with a single acquiring integration, custom checkout, and automated reconciliation for a single currency is the smaller build. A full platform with multi-provider routing, multi-currency support, marketplace split payments, and fraud controls is the larger one. The largest cost variables are the number of acquiring integrations, marketplace payout complexity, and reconciliation depth. We scope every project before pricing and deliver at a fixed cost.